Taxcharcha
Income TaxLatestRecent Case Laws

the provisions of Sec.2(22)(e) were not applicable since the payment was mere reimbursement of expenditure by M/s PHL – ITAT Mumbai

M/S ADMACH AUTO LIMITED, ITA NO. 9543/DEL/2019

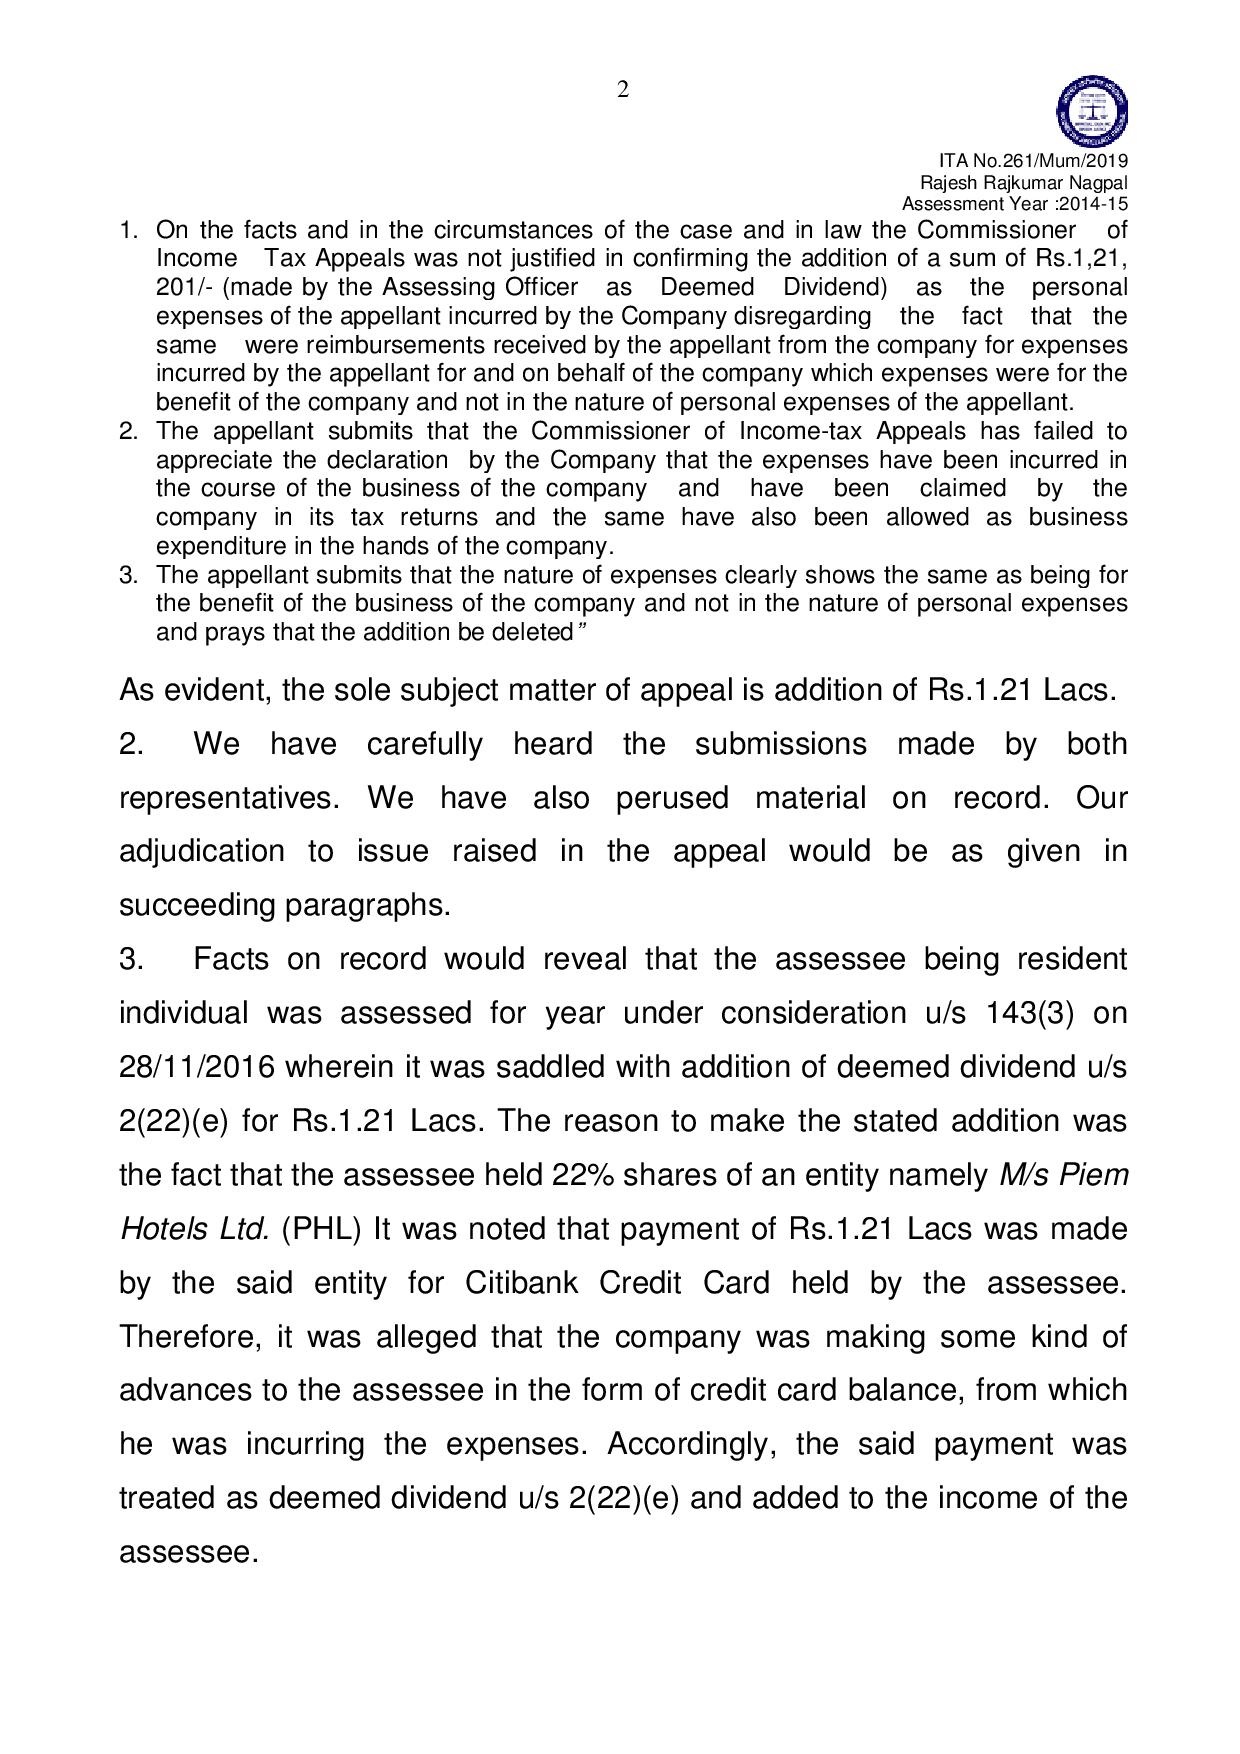
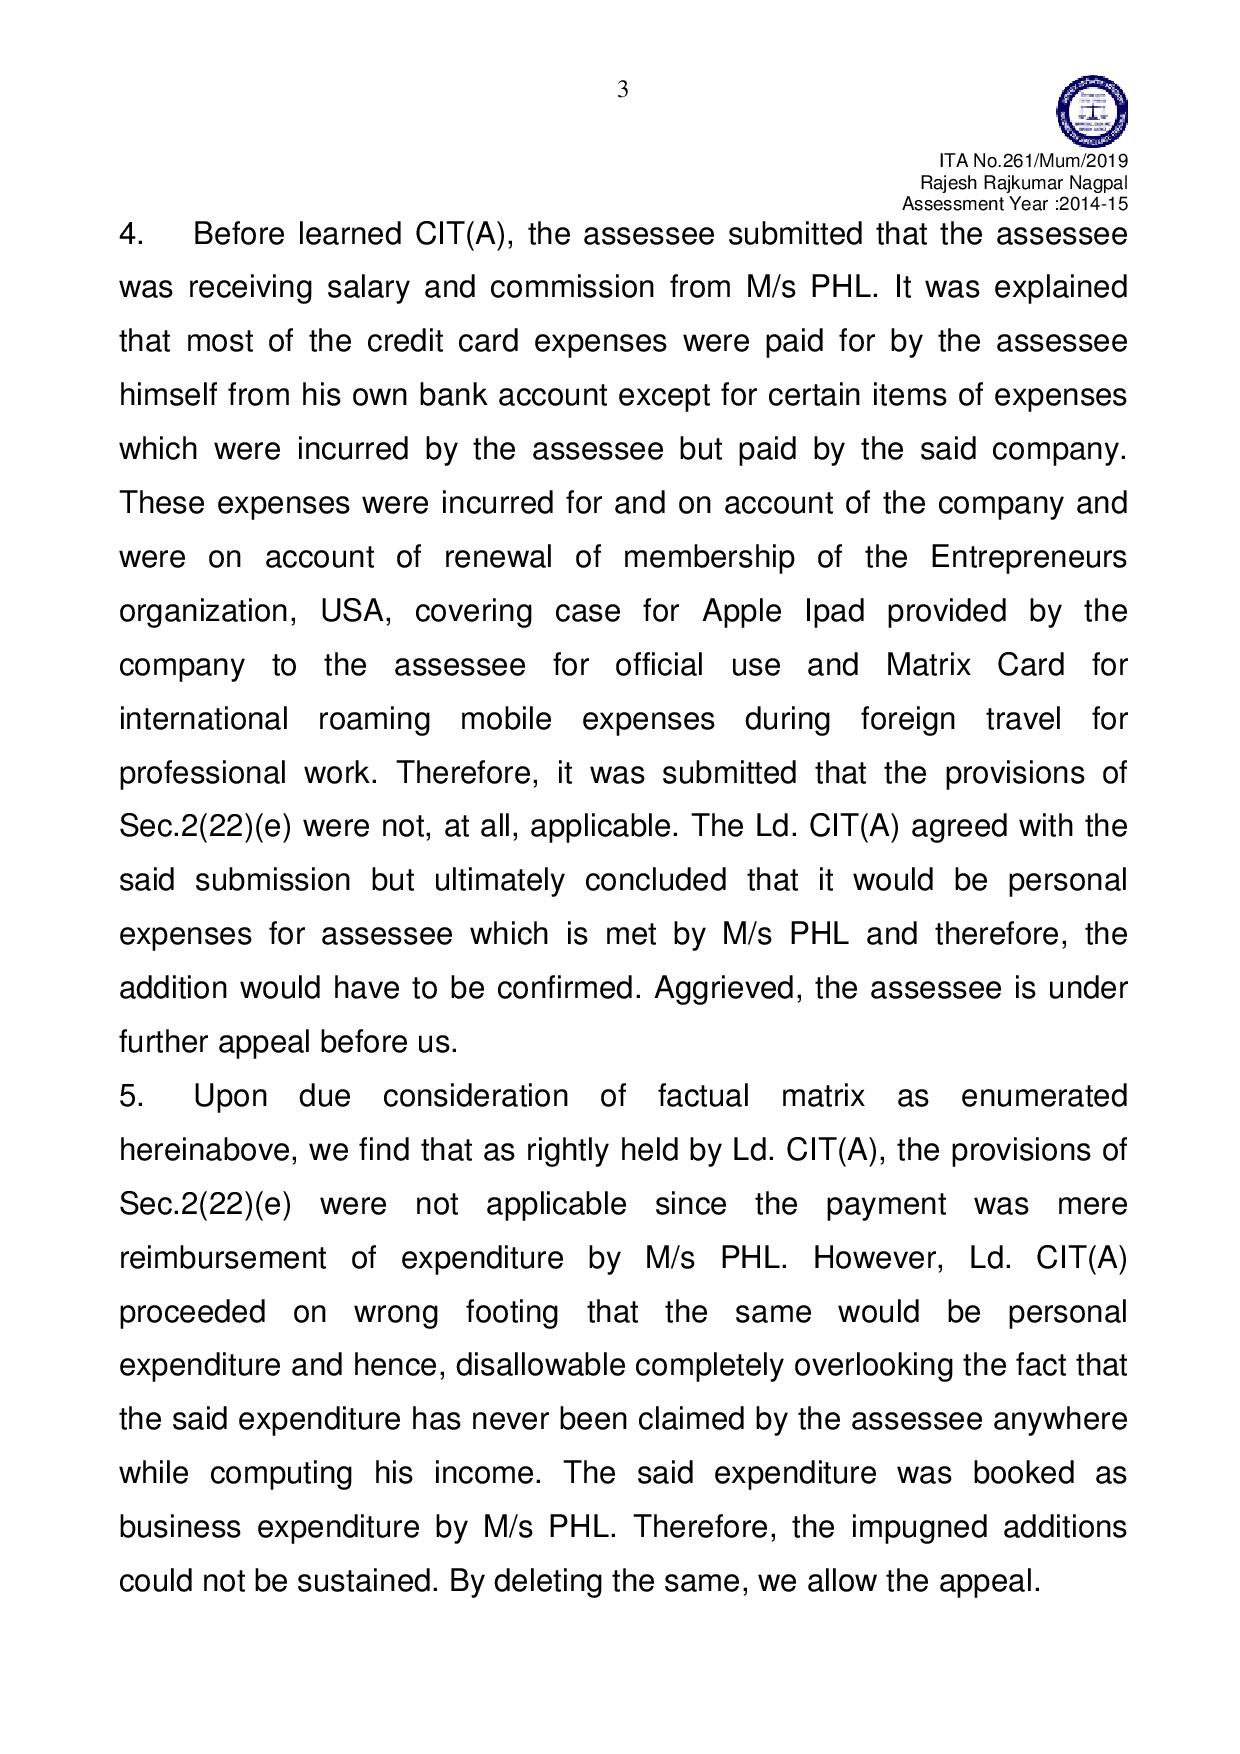
The provisions of Sec.2(22)(e) were not applicable since the payment was mere reimbursement of expenditure by M/s PHL. However, Ld. CIT(A) proceeded on wrong footing that the same would be personal expenditure and hence, disallowable completely overlooking the fact that the said expenditure has never been claimed by the assessee anywhere while computing his income.

The said expenditure was booked as  business expenditure by M/s PHL. Therefore, the impugned additions could not be sustained. By deleting the same,  ITAT allow the appeal.
Rajesh Rajkumar Nagpal ITA no. 261

Related posts

Relaxation of time for filing forms related to creation or modification of charges under the Companies Act 2013

Team Taxcharcha

ICAI representation to CBDT for Tax audit due date extension dated 17th September 2018

Team Taxcharcha

CBDT issues explanatory notes to the provisions of the Finance Act, 2018 on 26.12.2018 – Circular no.8/2018 , CBDT

Team Taxcharcha